How to Calculate Cost of Goods Sold: The Hidden Profit Lever Every Business Ignores
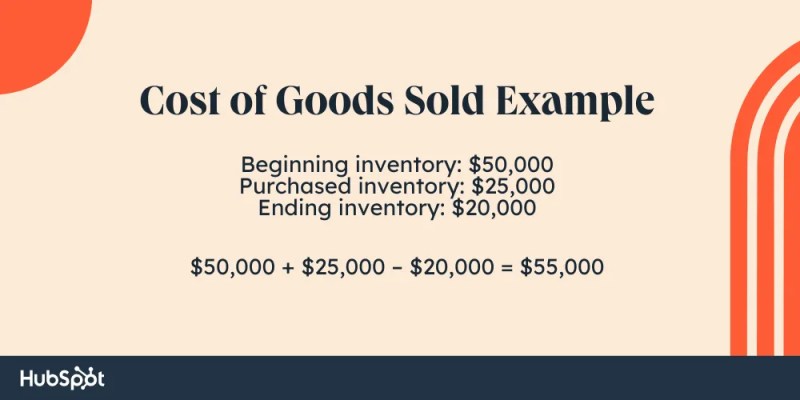
Businesses that fail to accurately track how to calculate cost of goods sold (COGS) are essentially flying blind—overpricing products that could dominate markets or underpricing those that bleed margins. The distinction between a thriving enterprise and one teetering on financial instability often hinges on this single metric. Yet, many entrepreneurs and finance teams treat COGS as an afterthought, buried in spreadsheets or delegated to generic accounting software without true understanding. The reality? COGS isn’t just a line item—it’s the foundation upon which pricing strategies, tax obligations, and investor confidence are built.
The misconception that COGS is a static number—something to be glanced at during tax season—couldn’t be further from the truth. In dynamic markets where supply chains fluctuate daily and raw material costs swing with geopolitical tensions, static calculations lead to catastrophic misjudgments. Take the 2022 semiconductor shortage, which forced automakers to either absorb higher costs or slash production. Those who recalculated COGS in real time adjusted prices swiftly; others faced quarterly losses. The difference wasn’t luck—it was precision in how to calculate cost of goods sold.
What separates high-performing businesses from the rest isn’t just access to capital or cutting-edge tech—it’s the ability to dissect COGS with surgical accuracy. Whether you’re a solopreneur selling handmade ceramics or a Fortune 500 manufacturer, the principles remain the same: direct costs must be isolated, indirect expenses must be allocated judiciously, and every dollar spent on production must be accounted for with forensic detail. This isn’t theoretical; it’s the difference between a 10% profit margin and a 30% one.
The Complete Overview of How to Calculate Cost of Goods Sold
At its core, understanding how to calculate cost of goods sold (COGS) is about answering one deceptively simple question: What did it truly cost to produce the goods you sold? The answer isn’t just the sticker price of materials or the hourly wage of workers—it’s a meticulously constructed equation that accounts for labor, overhead, and even the depreciation of machinery used in production. The formula itself is straightforward—Beginning Inventory + Purchases – Ending Inventory = COGS—but the devil lies in the execution. Direct costs (like fabric for a clothing line or steel for a manufacturer) are easy to quantify, but indirect costs (such as factory rent or utility bills) require allocation methods that can vary by industry. A bakery might allocate oven depreciation per batch, while a tech startup might spread R&D costs across product lifecycles. The key is consistency: once you choose a method, you must apply it uniformly to avoid skewing financial statements.The stakes are higher than most realize. COGS directly impacts gross profit—the figure investors and lenders scrutinize first. Understate COGS, and you’ll overstate profitability, attracting predatory investors or triggering audits. Overstate it, and you’ll price yourself out of competitive markets. The margin between these extremes is where businesses either thrive or fail. Take the example of a mid-sized electronics manufacturer that misclassified a portion of its R&D expenses as COGS. When auditors caught the error, the company had to restate three years of earnings, eroding shareholder trust and triggering a 20% stock drop. The lesson? How you calculate COGS isn’t just an accounting exercise—it’s a strategic imperative.
Historical Background and Evolution
The concept of COGS traces back to the Industrial Revolution, when factories replaced artisan workshops and inventory management became a critical function. Early accountants in the 19th century developed the idea of "cost of sales" to distinguish between expenses tied to production and those unrelated to revenue generation. The shift from agrarian economies to mass production demanded a new language for finance, and COGS became that language. By the early 20th century, standardized accounting principles—later codified in frameworks like GAAP (Generally Accepted Accounting Principles)—solidified COGS as a non-negotiable metric. The rise of corporations accelerated its importance, as shareholders required transparency into production efficiency to justify investments.Today, how to calculate cost of goods sold has evolved alongside technology. Traditional manual methods—where ledger books tracked inventory via pen and paper—have been replaced by ERP systems like SAP and Oracle, which automate COGS calculations in real time. However, the fundamental principles remain unchanged: direct materials, direct labor, and manufacturing overhead must still be accounted for with precision. The difference now is in the granularity. Modern businesses can track COGS by product line, customer segment, or even individual transactions, thanks to data analytics. Yet, for all the advancements, the core question persists: What does it cost to turn raw inputs into sold goods? The answer still hinges on accurate, methodical calculation.
Core Mechanisms: How It Works
The mechanics of how to calculate cost of goods sold begin with inventory valuation. Businesses must choose between FIFO (First-In, First-Out), LIFO (Last-In, First-Out), or Weighted Average Cost methods, each with distinct implications. FIFO, for instance, assumes the oldest inventory is sold first, which can understate COGS in inflationary periods but aligns with physical flow in many industries. LIFO, conversely, sells the most recent inventory first, reducing taxable income during high-price environments—a tactic popular among manufacturers. The weighted average method smooths out fluctuations by averaging all inventory costs, offering stability but obscuring price volatility. The choice isn’t arbitrary; it’s a strategic decision that affects tax liabilities and financial reporting. A retailer in a deflationary market might prefer FIFO to reflect lower historical costs, while a manufacturer facing rising material prices might opt for LIFO to defer taxes.Table of Contents
- The Complete Overview of How to Calculate Cost of Goods Sold
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can small businesses afford automated COGS systems?
- Q: How often should COGS be recalculated?
- Q: What’s the most common mistake in COGS calculation?
- Q: Does COGS include shipping and handling?
- Q: How does COGS affect tax deductions?
- Q: Can COGS be negative?
- Q: How do service-based businesses calculate COGS?
- Q: What’s the difference between COGS and operating expenses?
Beyond valuation, COGS incorporates direct costs—expenses directly tied to production, such as raw materials and wages of production-line workers—and indirect costs, like factory rent, utilities, and equipment depreciation. Allocating indirect costs requires judgment. A common approach is the activity-based costing (ABC) method, which assigns overhead based on resource consumption (e.g., machine hours or square footage used). For example, a textile mill might allocate electricity costs to each fabric batch based on the number of hours spent on looms. The precision here is critical: misallocating overhead can distort product profitability. A business might think a product is highly profitable when, in reality, it’s subsidized by another line. The solution? Regular audits of cost drivers and adjustments to allocation bases.
Key Benefits and Crucial Impact
The impact of mastering how to calculate cost of goods sold extends far beyond balance sheets. It dictates pricing strategies, influences investor confidence, and even shapes supply chain decisions. Businesses that treat COGS as a dynamic metric—continuously refined and analyzed—gain a competitive edge. They can identify unprofitable product lines before they drain resources, negotiate better terms with suppliers, and pivot production when costs spike. The alternative? Operating in the dark, where decisions are based on gut feeling rather than data. Consider a case study: A mid-sized furniture manufacturer noticed its COGS for upholstered chairs was creeping up due to rising fabric costs. By recalculating COGS and reallocating overhead, they discovered that a premium fabric line was actually unprofitable at current prices. The fix? A targeted price increase for that line, which restored margins without alienating customers.> "COGS isn’t just a number—it’s the DNA of your business. Get it wrong, and every other financial decision follows suit." — David Patrikalakis, CFO of a Fortune 500 industrial conglomerate
Major Advantages
- Accurate Pricing: COGS provides the floor for pricing. Without it, businesses risk selling below cost, eroding profitability. A well-calculated COGS ensures prices cover all expenses while remaining competitive.
- Tax Optimization: Choosing the right inventory valuation method (e.g., LIFO in inflationary periods) can legally reduce taxable income, freeing up capital for reinvestment.
- Investor Confidence: Financial statements with precise COGS calculations signal discipline and transparency, making the business more attractive to investors and lenders.
- Supply Chain Efficiency: COGS data highlights where costs are bloated—whether due to inefficient suppliers, wasteful processes, or outdated equipment—allowing for targeted improvements.
- Risk Mitigation: By tracking COGS in real time, businesses can anticipate cash flow crunches, adjust production volumes, or renegotiate contracts before cost overruns spiral.

Comparative Analysis
| Manual Calculation (Spreadsheets) | Automated Systems (ERP/Accounting Software) |
|---|---|
|
|
| FIFO Valuation | LIFO Valuation |
|
|
| Activity-Based Costing (ABC) | Traditional Absorption Costing |
|
|
Future Trends and Innovations
The future of how to calculate cost of goods sold is being reshaped by AI-driven predictive analytics and blockchain-based supply chain transparency. Machine learning models can now forecast COGS fluctuations by analyzing supplier contracts, weather patterns (for agricultural inputs), and geopolitical risks in real time. For example, a coffee roaster might use AI to adjust COGS projections based on predicted bean harvests in Brazil or Colombia. Meanwhile, blockchain is enabling immutable records of every transaction in the supply chain—from raw material sourcing to final sale—eliminating discrepancies in cost allocation. Early adopters in industries like pharmaceuticals and luxury goods are already seeing COGS accuracy improve by up to 30% through these technologies.Another emerging trend is dynamic COGS allocation, where costs are recalculated in real time based on actual usage rather than historical averages. This is particularly relevant for businesses with volatile demand, such as event planners or seasonal retailers. Imagine a holiday decor company that adjusts COGS for each batch of ornaments based on the exact amount of glitter and packaging used—no more averaging. The result? Pinpoint accuracy in profitability analysis. As these innovations mature, the businesses that master how to calculate cost of goods sold won’t just be reacting to financial data—they’ll be predicting it before it happens.

Conclusion
How to calculate cost of goods sold is more than an accounting exercise—it’s the cornerstone of financial health. The businesses that succeed in the coming decade won’t be those with the lowest overhead or the most aggressive pricing; they’ll be the ones that treat COGS as a strategic lever, constantly refined and optimized. The tools are evolving, from AI to blockchain, but the core principle remains: Know exactly what it costs to produce what you sell. Ignore this, and you’re gambling with your margins. Embrace it, and you’re building a business that doesn’t just survive—it dominates.The paradox of COGS is that it’s both simple and profoundly complex. The formula is basic, but the execution demands rigor. Whether you’re a startup or a multinational, the time to audit your COGS calculation is now. The difference between a 10% profit margin and a 30% one often comes down to a few well-placed decimal points—and the discipline to track them correctly.
Comprehensive FAQs
Q: Can small businesses afford automated COGS systems?
A: Yes, but prioritize based on scale. Cloud-based accounting tools like QuickBooks or Xero offer automated COGS tracking at a fraction of the cost of ERP systems. For manual processes, templates in Excel or Google Sheets can streamline calculations without breaking the bank. The key is starting with the essentials—direct materials, labor, and overhead allocation—and scaling up as revenue grows.
Q: How often should COGS be recalculated?
A: Ideally, COGS should be recalculated with every financial period—monthly, quarterly, or annually—depending on your industry’s volatility. High-turnover businesses (e.g., retail, food service) may need monthly recalculations to account for fluctuating ingredient or inventory costs. Low-turnover industries (e.g., custom furniture) might suffice with quarterly reviews. Real-time tracking via ERP systems eliminates this lag entirely.
Q: What’s the most common mistake in COGS calculation?
A: The most frequent error is overlooking indirect costs or allocating them arbitrarily. Many businesses treat overhead as a single pool, distributing it equally across products without considering actual usage. For example, a factory might allocate rent based on square footage, but a more accurate method would tie it to machine hours or production volume. Another mistake is mixing direct and indirect labor costs—only wages directly tied to production (e.g., assembly-line workers) belong in COGS.
Q: Does COGS include shipping and handling?
A: It depends on the context. If shipping is freight-in (cost to bring materials to your facility), it’s part of COGS as a direct material cost. If it’s freight-out (cost to ship finished goods to customers), it’s typically classified as a selling expense, not COGS. However, some businesses include outbound shipping in COGS if it’s a significant and variable cost tied to production (e.g., a custom manufacturer with unique shipping requirements per order). Always align with your industry standards and tax regulations.
Q: How does COGS affect tax deductions?
A: COGS directly reduces taxable income, making accurate calculation critical for tax optimization. The inventory valuation method you choose (FIFO, LIFO, or average cost) impacts reported COGS and thus taxable profit. For instance, LIFO can defer taxes in inflationary periods by increasing COGS (lowering taxable income), while FIFO may increase taxes by reducing COGS. Additionally, depreciation on production equipment is often included in COGS, providing another tax deduction. Consult a tax advisor to ensure your COGS strategy aligns with local laws—some countries restrict LIFO or require specific allocation methods.
Q: Can COGS be negative?
A: No, COGS cannot be negative in standard accounting. However, a negative gross profit (revenue minus COGS) is possible and signals a serious issue—you’re selling products for less than it costs to produce them. This often happens due to pricing errors, cost overruns, or inventory obsolescence. If you encounter negative gross profit, audit your COGS calculation immediately to identify misallocations, supplier issues, or unprofitable product lines. It’s a red flag that demands corrective action.
Q: How do service-based businesses calculate COGS?
A: Service businesses don’t have traditional "goods," but they still track direct costs of service delivery. COGS for services might include:
- Direct labor (e.g., consultant hours billed to a client).
- Materials used in service delivery (e.g., printing costs for a marketing agency).
- Subcontractor expenses (e.g., freelance designers for a web dev firm).
Q: What’s the difference between COGS and operating expenses?
A: COGS represents direct costs tied to producing goods sold, while operating expenses (OPEX) cover all other business costs. Examples:
- COGS: Raw materials, production labor, factory depreciation.
- OPEX: Marketing, rent, salaries (non-production), utilities.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Seuclienteoculto.